
Puma’s third-quarter results offer investors fresh hope as the German sportswear giant cuts inventory, strengthens its financial position and prepares for a potential comeback in China through its partnership with Anta Sports.
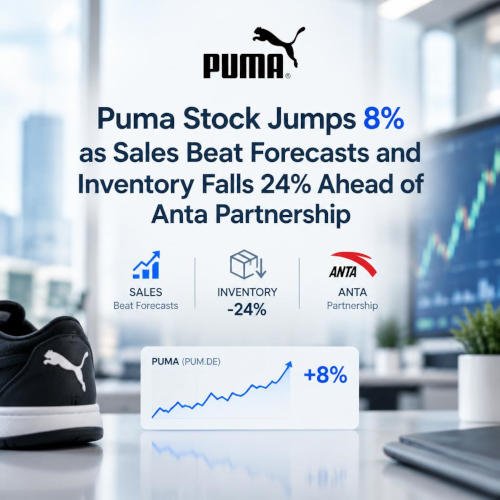
Puma is showing early signs of progress in its efforts to rebuild its global sportswear business. The German athletic apparel manufacturer reported third-quarter sales above analysts’ expectations on October 30, 2026, while significantly reducing its inventory levels. The results helped lift investor confidence, sending Puma shares up approximately 8% during Friday’s trading session.
Although the company continues to face declining sales and intense competition from Adidas and Nike, its latest financial results suggest that management is making progress on an important business priority: reducing excess inventory and improving operational efficiency.
The development comes as Puma advances its partnership with Chinese sportswear giant Anta Sports, a move that could create new opportunities in China’s competitive athletic footwear and apparel market.
For investors following Puma stock, sportswear industry trends, retail earnings and global consumer spending, the latest results provide several important signals about the company’s recovery strategy.
Puma Q3 2026 Earnings: Sales Beat Estimates Despite Weak Consumer Demand
Puma’s third-quarter performance delivered a mixed financial picture. While revenue declined compared with the previous year, the company managed to outperform analysts’ expectations.
According to its October 30 financial announcement, Puma generated €1.776 billion in third-quarter sales, compared with €1.870 billion during the same period in 2025. This represented a 5% decline on a reported basis and a 6.3% decrease after adjusting for currency movements.
However, analysts had expected quarterly revenue of approximately €1.75 billion. Puma’s ability to exceed that forecast provided some reassurance to investors concerned about the company’s declining sales momentum.
The improvement was particularly important because Puma has been implementing business restructuring measures to strengthen its brand positioning and eliminate less profitable distribution channels.
The company is also working to reduce its dependence on wholesale retailers while developing its direct-to-consumer business through physical stores and e-commerce platforms.
Puma’s direct-to-consumer revenue increased 1.2% on a currency-adjusted basis to €588.3 million. E-commerce sales performed better, increasing 7.8%, despite reduced promotional activity.
Wholesale revenue, however, declined 9.6% to €1.188 billion, reflecting weaker demand and the company’s decision to reduce less desirable business with mass-market retailers. PUMA SE
Puma Inventory Falls 24.3%, Offering Relief to Investors
Inventory reduction emerged as one of the strongest positive developments in Puma’s latest earnings report.
The company reduced its inventory by 24.3% to approximately €1.61 billion as of September 30, compared with €2.12 billion a year earlier.
This improvement largely resulted from lower purchasing volumes and tighter inventory management.
For sportswear manufacturers, excessive inventory can create significant financial pressure. When companies hold more shoes, clothing and accessories than customers want to purchase, they may need to introduce heavy discounts to clear unsold products.
The improvement could help the company reduce discounting pressure, manage working capital more effectively and create room for new product launches.
However, lower inventory does not automatically guarantee stronger future sales. Puma will still need to demonstrate that consumers are returning to its products and that retailers are willing to increase orders.
Puma Stock Rises 8% After Quarterly Earnings Announcement
Investors responded positively to Puma’s financial update.
The company’s shares climbed approximately 8% during Friday’s trading session, putting the stock on course for its strongest daily performance since February.
The market reaction reflected optimism about the company’s inventory reduction, better-than-expected revenue and progress on its restructuring strategy.
Puma stock has faced pressure as investors evaluated declining consumer demand, competition from major sportswear brands and the company’s efforts to rebuild its market position.
The latest results provided some evidence that management’s turnaround strategy is beginning to address operational weaknesses.
Nevertheless, investors should distinguish between a positive short-term stock market reaction and a confirmed long-term recovery.
Puma continues to face financial challenges, including operating losses and higher operating expenses.
Its ability to improve profitability, generate sustainable cash flow and restore revenue growth will remain important factors for investors evaluating the company’s future performance.
Profit Margins Improve as Puma Focuses on Cost Reduction
Puma’s third-quarter gross profit margin improved significantly, reaching 49.5%, compared with 45.4% in the corresponding period last year.
The improvement reflected lower sourcing prices, favourable currency movements, channel mix and reduced freight expenses. Tariff refunds also contributed to the increase.
However, stronger gross margins did not translate into positive operating earnings.
Puma reported an operating loss (EBIT) of €11.4 million for the quarter, compared with operating income of €16.2 million a year earlier.
Higher operating expenses, marketing investments and costs associated with the company’s growing direct-to-consumer operations continued to affect profitability.
The company also reported free cash flow of €92 million, a considerable improvement from negative €43 million in the third quarter of 2025.
This improvement was supported by better working capital management, lower tax payments and reduced capital expenditure.
For investors examining Puma’s financial health, the stronger cash flow and lower inventory are encouraging developments. However, sustained improvements in operating income will be necessary before the turnaround can be considered firmly established. PUMA SE
ANTA Sports Partnership Creates New Opportunities for Puma in China
Another major development influencing investor sentiment is Puma’s relationship with Chinese sportswear company ANTA Sports.
On October 7, 2026, ANTA Sports completed its acquisition of a 29.06% stake in Puma from Artémis SAS, the investment company of the Pinault family.
The transaction, valued at approximately €1.51 billion, made ANTA Puma’s largest shareholder.
The partnership could provide Puma with access to valuable market knowledge, distribution capabilities and consumer insights in China.
China represents an important growth opportunity for international sportswear manufacturers. Its large consumer market and interest in athletic footwear, running apparel and lifestyle fashion make it strategically important for global brands.
Puma CEO Arthur Hoeld has indicated that the partnership creates opportunities to strengthen the company’s position in China and unlock its broader international potential.
ANTA has also stated that it intends to support Puma’s global development while respecting its brand identity, independent governance and corporate culture.
This distinction matters because ANTA’s investment does not mean Puma is becoming a subsidiary of the Chinese sportswear group.
Instead, the arrangement creates an opportunity for strategic cooperation while Puma maintains its own identity.
For investors, the key question is whether this relationship can translate into stronger sales, better retail distribution and improved brand visibility in China. Anta
China Growth Offers Support as Europe and North America Remain Weak
Puma’s regional sales performance highlights why the Chinese partnership could become important.
Asia/Pacific recorded 10% currency-adjusted sales growth during the third quarter, reaching €394.6 million.
Greater China delivered 3.5% growth, supported by the company’s direct-to-consumer business and expanding e-commerce distribution.
Puma’s Speedcat footwear range remained particularly popular among Asian consumers, helping support demand for its low-profile sneaker category.
However, performance was considerably weaker in other regions.
EMEA sales declined 11.5% on a currency-adjusted basis to €801.2 million. The Americas region recorded an 8.1% decline, while North American sales fell 17.2%.
These figures demonstrate that Puma’s recovery remains uneven.
The company needs to rebuild consumer demand in established markets while taking advantage of growth opportunities in Asia.
Its ability to balance these priorities could determine how quickly the business returns to sustainable revenue growth.
Puma Updates Its 2026 Financial Outlook
Alongside its third-quarter earnings, Puma updated its financial guidance for the remainder of 2026. Puma now expects 2026 EBIT to fall between €80 million and €130 million, compared with its previous forecast range of €50 million to €150 million.
The company also reduced its capital expenditure expectations to below €150 million, down from its earlier estimate of approximately €200 million.
These adjustments indicate that management is prioritising financial discipline, controlling expenses and concentrating investments on important business operations.
Puma’s cost-efficiency programme remains central to its turnaround strategy.
The company must balance spending on advertising, product innovation and retail expansion against the need to protect profitability.
Its investments in running technology, digital infrastructure and direct-to-consumer channels could support longer-term competitiveness.
Can Puma Compete With Nike and Adidas Again?
Puma faces a difficult competitive environment.
Nike and Adidas have established strong global distribution networks, brand recognition and customer loyalty.
Puma wants to strengthen its position by improving its performance-sportswear credentials while maintaining its appeal in lifestyle footwear.
Puma Stock Outlook
Puma’s latest quarterly earnings provide several encouraging signals, particularly the 24.3% inventory reduction, stronger free cash flow and improved gross profit margin.
The ANTA Sports partnership also introduces a potentially important growth opportunity in China
Investors following Puma stock should pay attention to several developments over the coming quarters:
- Revenue growth: Whether Puma can reverse declining sales and improve demand across major markets.
- Inventory management: Whether inventory levels remain under control without creating product shortages.
- Profit margins: Whether lower sourcing costs and operational efficiencies translate into stronger operating earnings.
- China expansion: Whether the ANTA partnership improves distribution, retail performance and brand visibility.
- Cash flow: Whether Puma can maintain positive free cash flow while investing in its long-term business strategy.
The next stage of Puma’s recovery will depend on its ability to convert operational improvements into stronger financial performance.
For now, the latest results have given investors a reason to become more optimistic, but a sustained recovery will require consistent progress beyond inventory reductions.
The bottom line: Puma’s third-quarter results suggest that its restructuring strategy is gaining traction. Better inventory management, improving cash flow and the ANTA partnership offer potential support. However, restoring consumer demand and returning to operating profitability remain the company’s biggest challenges heading into 2027.
Reference Links
- PUMA Official Q3 2026 Financial Results
- ANTA Sports Acquisition Announcement
- Reuters – Puma Q3 Earnings and Inventory Reduction
Editorial note: This article distinguishes reported sales declines from currency-adjusted performance and does not present ANTA’s minority investment as a full acquisition of Puma.
