USA Business and Finance: Bringing an article on the latest business and finance tips in the USA, and recent news analysis and discussion. We hope you enjoy this daily America Business and finance news on a wide range of topics today.
Here’s a human-friendly, SEO-conscious article of approximately 1,400 words, written in short paragraphs with practical tips and real economic reporting from 2026. It looks ahead to 2027 without treating economic forecasts as guarantees.
The American economy continues to create opportunities for people who want to start a business, improve their finances, or build long-term wealth. However, higher living costs, changing interest rates, and uncertainty about future economic conditions mean that households and business owners need to make thoughtful financial decisions.
As 2026 moves toward its final months, many Americans are already thinking about 2027. Should they save more money, pay off debt, invest in the stock market, or start a small business? The answer depends on personal circumstances, but a few practical principles can help people prepare for the year ahead.
Understanding the US Economy
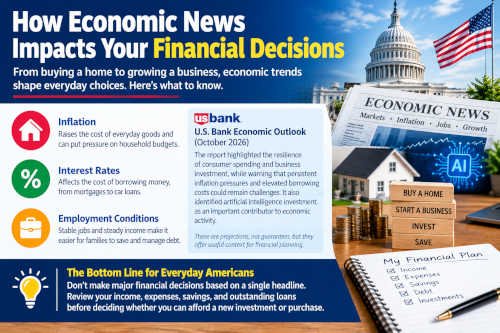
Economic news can influence everyday decisions, from buying a home to expanding a business. Inflation affects household budgets, while interest rates influence the cost of borrowing money. Employment conditions also matter because steady income makes it easier for families to save and manage debt.
An October 2026 economic outlook from U.S. Bank highlighted the resilience of consumer spending and business investment while warning that persistent inflation pressures and elevated borrowing costs could remain challenges. Its forecast also identified artificial intelligence investment as an important contributor to economic activity. These are projections, not guarantees, but they offer useful context for financial planning.
For normal citizens/ ordinary Americans, the practical lesson is simple: avoid making major financial decisions based on a single headline. Review your income, expenses, savings, and outstanding loans before deciding whether you can afford a new investment or purchase.
If your household budget is already tight, building financial stability may be more valuable than chasing a potentially high return. People with stronger financial foundations generally have more flexibility when unexpected expenses arise.
Build an Emergency Fund Before Taking Bigger Risks
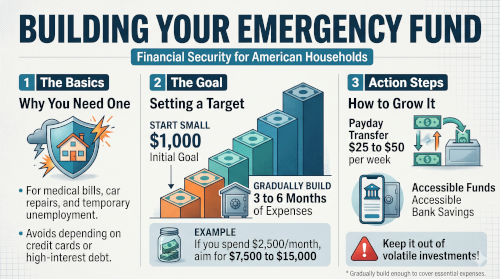
An emergency fund is one of the most useful financial tools for American households. That is to say It provides money for unexpected medical bills, car repairs, temporary unemployment, or other expenses without requiring you to depend on credit cards.
A reasonable initial aim is to save $1,000, then gradually build enough money to cover three to six months of essential expenses. The right amount depends on your job security, family responsibilities, health costs, and access to other financial resources.
For example, someone who spends $2,500 monthly on essential expenses could aim for an emergency fund of $7,500 to $15,000. That amount may take time to accumulate, so there is no need to achieve the full target immediately.
Proceed With a manageable automatic transfer each payday. Even $25 or $50 per week can make a difference over time.
Have emergency savings somewhere accessible, such as an insured bank savings account. Money needed for immediate expenses generally should not be placed in volatile investments that could lose value when you need to withdraw it.
Manage Credit Card Debt and High-Interest Loans
Debt management should be a major financial priority in late 2026 and throughout 2027. Credit card balances can become expensive when interest charges accumulate, especially if you regularly pay only the minimum amount due.
Begin by listing every debt, its balance, interest rate, and minimum monthly payment. Continue making at least the required payments on all accounts, then direct additional money toward the debt with the highest interest rate.
This approach, often called the debt avalanche method, can reduce the total interest paid over time. Alternatively, the debt snowball method focuses on paying off the smallest balance first, which some people find more motivating.
Before consolidating debt or transferring a balance to another credit card, check the fees, promotional interest period, and rate that applies afterward. A lower advertised rate does not automatically mean a better deal.
Ensure you are not taking out new loans simply to maintain an expensive lifestyle. If your debt payments are consuming a large portion of your income, consider adjusting discretionary spending and contacting creditors before missed payments become a serious problem.
Prepare Your Small Business for Changing Costs
Small businesses remain an important part of the US economy, but owners must carefully manage expenses to protect their profits. Rent, insurance, payroll, supplies, shipping, and financing can all affect how much money a business keeps.
A September 23, 2026, survey released by the Federal Reserve Banks of Richmond and Atlanta and Duke University’s Fuqua School of Business found that approximately 20% of surveyed financial executives said interest rates and the possibility of further increases were major concerns. The survey also found that 20% of companies reported financial constraints that prevented them from covering costs or pursuing opportunities.
Although the survey reflects the views of participating companies rather than every American business, it highlights an important issue: access to cash can determine whether a business can survive a difficult period or take advantage of new opportunities.
Business owners should review their expenses at least once a month. Identify subscriptions that are no longer useful, compare supplier prices, and negotiate contracts when possible.
It is also wise to separate business and personal finances. A dedicated business account makes it easier to track income, calculate expenses, prepare tax records, and understand whether the company is genuinely profitable.
Before expanding, check whether the business can afford the additional costs even if sales grow more slowly than expected.
Use Artificial Intelligence Carefully in Business
Artificial intelligence has become a practical tool for many American businesses. Small companies can use AI-powered software to help draft marketing material, organize customer questions, summarize documents, analyze sales trends, and automate repetitive administrative tasks.
These tools may help a small business operate more efficiently without immediately hiring additional staff. However, the benefits depend on choosing the right tools and using them responsibly.
Start by identifying a task that consumes too much time. For example, an online store might use automation to organize customer inquiries, while a local service company could use scheduling software to reduce administrative work.
Compare subscription costs with the time and money saved. A tool that costs $100 each month should deliver enough value to justify that expense.
Protect customer information and avoid entering confidential financial records or sensitive personal data into AI systems without understanding their privacy and security arrangements. Important legal, tax, and financial decisions should also be checked by qualified professionals.
For 2027, the best approach is not necessarily to adopt every new technology. It is to use tools that solve real problems, improve customer service, or reduce unnecessary costs.
Invest for the Long Term Instead of Chasing Headlines
The stock market can offer opportunities to build wealth, but prices can rise and fall sharply. News about interest rates, corporate earnings, tariffs, technology companies, and international conflicts can influence investor sentiment.
An October 2026 analysis from U.S. Bank discussed how corporate earnings, consumer spending, trade policies, and borrowing costs were shaping financial markets. Its central lesson for investors was the importance of discipline, diversification, and matching investments to personal goals rather than reacting to every market movement.
Before investing, establish when you will need the money. Cash required for rent, emergencies, or a near-term home purchase generally should not be exposed to substantial stock-market risk.
For longer-term goals, diversified funds may provide exposure to many companies instead of depending on the performance of a single stock. Investors should still understand fees, risks, and the possibility of losses.
Consider reviewing your portfolio periodically rather than checking it constantly. Frequent trading based on short-term headlines can lead to unnecessary costs and decisions driven by fear or excitement.
No investment strategy guarantees profits. Be especially cautious about social media posts promising extraordinary returns, secret trading methods, or risk-free opportunities.
Review Your Taxes and Retirement Contributions
Tax planning is another useful step before the end of 2026. Employees, freelancers, contractors, and small business owners may have different filing obligations and opportunities to organize their finances more effectively.
Keep records of income, eligible expenses, charitable donations, and other documents relevant to your tax situation. Self-employed workers should pay particular attention to estimated tax payments and records of business expenses.
The Internal Revenue Service publishes annual inflation adjustments and guidance about federal tax rules. Its official website should be the first place to check current requirements rather than relying on an old article or an unverified social media post.
Retirement contributions also deserve attention. Depending on eligibility and the account involved, contributions to employer-sponsored plans or individual retirement accounts may help people prepare for retirement and could offer tax advantages.
If your employer offers matching retirement contributions, review the plan rules to understand how the match works. Leaving an available employer match unused may mean missing out on part of your compensation.
Before making a large contribution or withdrawal, check the applicable limits, eligibility rules, tax consequences, and deadlines for the relevant tax year.
Make a Realistic Plan for Buying a Home or Car
Large purchases can affect household finances for years. If you plan to buy a home or vehicle in 2027, start preparing before you apply for financing.
Review your credit reports, pay down manageable debts, and estimate the full cost of ownership. A home’s expenses include property taxes, insurance, maintenance, utilities, and potentially homeowners association fees. A car’s costs include insurance, fuel, repairs, registration, and depreciation.
Mortgage and auto loan rates can change with market conditions and lender policies. Do not assume that rates will fall by a specific amount in 2027.
Instead, calculate whether the purchase remains affordable under different interest-rate scenarios. If a modest increase in the monthly payment would strain your budget, consider a less expensive property or vehicle, a larger down payment, or delaying the purchase.
Compare loan offers from several lenders and look beyond the advertised monthly payment. The interest rate, loan term, fees, and total amount repaid are all important.
A lower monthly payment can sometimes hide a much longer loan and a higher overall cost.
Create a Simple Financial Plan for 2027
You do not need complicated spreadsheets or expensive financial software to organize your money. A simple monthly plan can help you understand where your income goes and where changes are possible.
Start by recording your take-home income and essential expenses. Then include debt payments, savings, insurance, retirement contributions, and discretionary spending.
Set three specific financial goals for 2027. For example, you might aim to save $3,000, reduce credit card debt by $2,000, or increase retirement contributions by a set percentage.
Make each goal measurable and give it a deadline. Divide larger targets into monthly amounts so you can track progress without feeling overwhelmed.
Review your plan every month. If your income changes or an unexpected expense appears, adjust the budget rather than abandoning it.
Families with irregular income may benefit from building a larger cash reserve and calculating essential expenses using a conservative estimate of their monthly earnings.
The purpose of a financial plan is not to predict every problem. It is to help you respond to problems without losing sight of your long-term priorities.
Watch These Business and Finance Trends in 2027
Several developments deserve attention as Americans prepare for 2027. Inflation, interest rates, consumer spending, employment, tax policy, and business investment may all affect household budgets and company decisions.
Artificial intelligence investment is another important trend. It may create opportunities for businesses that improve productivity, but companies should evaluate the costs and expected benefits before making substantial investments.
Trade policies and tariffs can also affect businesses that depend on imported products or international suppliers. Owners should understand where their products come from, compare alternative suppliers, and assess how changing costs might affect profit margins.
For investors, market valuations and corporate earnings will remain important considerations. A popular industry is not automatically a good investment at every price.
Economic forecasts differ, and conditions can change quickly. The Organisation for Economic Co-operation and Development has also highlighted risks involving energy prices, inflation, employment, and financial markets in its US economic analysis.
Rather than betting on one prediction, prepare for several possible outcomes. Keeping debt manageable, maintaining accessible savings, and diversifying investments can help households and businesses remain flexible.
Conclusion
The most useful business and finance tips for 2026 and 2027 are often straightforward: spend carefully, build emergency savings, manage expensive debt, keep accurate financial records, and invest according to your goals and tolerance for risk.
Small business owners should pay close attention to cash flow, operating costs, customer needs, and the real value of new technology. Employees and families can strengthen their financial position by reviewing budgets, preparing for major purchases, and making consistent progress toward retirement.
Nobody knows exactly how the US economy will perform throughout 2027. Interest rates, inflation, government policies, and international developments could change the outlook. That uncertainty makes preparation more valuable, not less.
You do not have to make every financial decision at once. Choose one practical improvement this month, measure the result, and build from there. Over time, steady decisions can put you in a stronger position to handle unexpected expenses, pursue business opportunities, and work toward greater financial security.
Reference links