
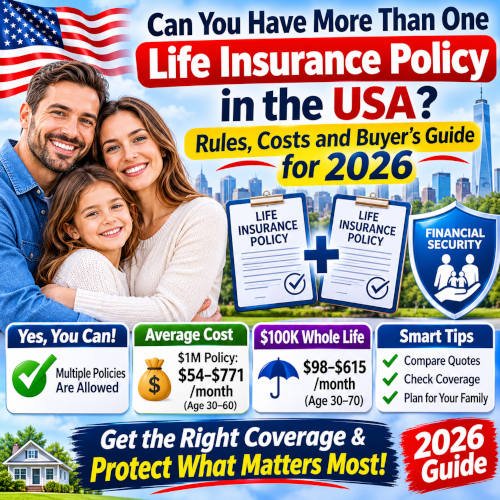
Insurance updates USA: Yes. You can have more than one life insurance policy in the United States, even if the policies come from different insurance companies. Many Americans use multiple policies to protect their families, cover a mortgage, replace lost income, or provide lifelong financial support.
However, buying additional coverage involves more than paying another premium. Insurers may review your existing policies, income, financial obligations, and total requested death benefit before approving an application.
This 2026 guide explains how multiple life insurance policies work, whether beneficiaries can collect from both, how much $1 million of coverage may cost, and what buyers should know about a $100,000 whole life policy.
Is It Possible to Have Two Life Insurance Policies in the USA?
Yes. There is generally no federal limit on the number of individual life insurance policies a person can own. You may purchase two or more policies from the same insurance company or different insurers.
For example, someone might have:
- A $500,000 term life policy to protect their family during their working years.
- A $250,000 employer-sponsored group life insurance policy.
- A $100,000 whole life policy for lifelong coverage and potential cash value.
In this example, the individual has $850,000 in total life insurance coverage, assuming all three policies remain active and the benefits are payable.
Each policy is a separate insurance contract. Insurers do not normally divide one death benefit between multiple policies simply because the insured person owns more than one.
However, applicants must disclose existing coverage when asked. Insurance companies evaluate whether the requested total coverage is financially reasonable. They may request income details, information about other policies, and the purpose of the additional protection.
According to MoneyGeek’s September 2026 review, people can hold multiple policies, but insurers may reject or reduce applications when the total requested coverage exceeds what their financial circumstances justify.
What Happens If I Have Two Life Insurance Policies?
If you own two valid life insurance policies and both remain active when you die, your beneficiaries can generally claim the death benefit under each contract.
For example:
| Policy | Death benefit |
|---|---|
| Policy A – 20-year term | $500,000 |
| Policy B – Whole life | $100,000 |
| Total potential benefit | $600,000 |
If both policies pay their full benefits, eligible beneficiaries could receive $600,000 in total.
The beneficiaries usually need to submit a separate claim to each insurance company. They may be asked for a certified death certificate, claim form, policy information, and identity documents.
There are important conditions. The policies must be valid and in force, premiums must be paid as required, and the claims must satisfy each contract’s terms. Insurers can investigate applications and claims when they identify material misrepresentations, fraud, or possible policy exclusions.
Does having two policies increase the payout? It can. Unlike health insurance, where coordination between insurers may apply, separate life insurance policies generally pay their own contractual death benefits when claims are approved.
Why Do People Buy Multiple Life Insurance Policies?
Buying more than one policy can make sense when a person’s financial responsibilities change over time.
Here are four common reasons:
1. Covering different financial responsibilities
A family may need enough coverage to replace income while children are young. A separate smaller policy could help cover final expenses or provide lifelong protection.
2. Combining employer and personal coverage
Many employers offer group life insurance as an employee benefit. However, employer coverage may be limited and may change when employment ends. An individual policy can provide additional protection outside the workplace.
3. Matching different coverage periods
A 30-year term policy might cover a mortgage and child-raising years, while a 10-year policy could cover a shorter financial obligation. This approach is sometimes called life insurance laddering.
4. Adding coverage after a major life event
Marriage, having children, buying a home, starting a business, or taking on significant debt can increase the amount of financial protection a family needs.
Before purchasing another policy, calculate the actual coverage gap. A second policy is useful only when the additional protection justifies its premium.
How Much Is a $1,000,000 Life Insurance Policy in 2026?
The cost of a $1 million life insurance policy depends on age, health, tobacco use, policy type, and term length.
MoneyGeek’s September 30, 2026 analysis of quotes from more than 30 insurers provides the following average monthly premiums for a $1 million, 20-year term life policy:
| Age | Women | Men |
|---|---|---|
| 30 | $54 | $67 |
| 40 | $86 | $109 |
| 50 | $194 | $262 |
| 60 | $545 | $771 |
These figures represent average quote estimates for applicants in the profiles used in the research, not guaranteed prices for every buyer. Actual offers can differ based on underwriting and insurer requirements.
For a 40-year-old, the difference between a $1 million and a smaller policy can be significant, but the right amount depends on family needs.
A useful starting calculation is:
Life insurance need = Outstanding debts + Future family expenses + Income replacement − Existing assets and coverage.
For example, a household may need money for mortgage payments, childcare, education, and several years of income replacement. A $1 million policy may be suitable for some families but excessive or insufficient for others.
Compare quotes from multiple insurers before choosing a policy. Check whether the premium is guaranteed for the full term and whether the coverage lasts long enough to meet your financial obligations.
How Much Is a $100,000 Whole Life Policy?
A $100,000 whole life insurance policy provides lifelong coverage as long as the policy remains in force under its contract. Unlike term life insurance, whole life insurance can also build cash value over time.
However, permanent coverage usually costs considerably more than term coverage with the same death benefit.
MoneyGeek’s October 29, 2026 analysis reports these average monthly whole life premiums for nonsmokers in average health:
| Age | Women | Men |
|---|---|---|
| 30 | $98 | $103 |
| 40 | $127 | $130 |
| 50 | $146 | $186 |
| 60 | $288 | $308 |
| 70 | $555 | $615 |
For comparison, a 40-year-old nonsmoker pays average monthly estimates of $127 for a woman and $130 for a man for $100,000 of whole life coverage.
The same research found that a $100,000, 20-year term policy at age 40 averages approximately $16 per month for women and $19 for men. This illustrates the substantial price difference between temporary and permanent coverage.
Whole life may suit buyers who want lifelong protection and predictable premiums. However, it is important to understand the policy’s guaranteed cash value, fees, dividend assumptions, surrender charges, and loan provisions before purchasing.
What Should You Check Before Buying a Second Life Insurance Policy?
Before applying for another policy, review these important factors:
- Existing coverage: Calculate the death benefits of all active individual and employer-sponsored policies.
- Financial justification: Make sure your requested coverage matches your income, debts, dependents, and financial responsibilities.
- Premium affordability: Check whether you can maintain every policy over the long term.
- Beneficiary details: Confirm that beneficiaries are correctly named and updated.
- Policy type: Compare term, whole life, and universal life based on your needs.
- Application accuracy: Disclose existing coverage and answer health and financial questions honestly.
- Employer coverage: Check whether workplace insurance is portable or convertible if you leave your job.
Do not cancel an existing policy before a replacement policy has been approved, issued, and reviewed. Otherwise, you could lose valuable protection or face higher premiums because of changes in age or health.
Also review the tax treatment. The IRS generally says life insurance death benefits paid because of the insured person’s death are not included in the beneficiary’s gross income. However, interest paid on proceeds may be taxable, and certain transferred policies or other arrangements can receive different treatment.
Frequently Asked Questions About Multiple Life Insurance Policies
Can I have two life insurance policies from different companies?
Yes. You can generally buy policies from different insurers. Each company conducts its own underwriting and may ask about your existing coverage.
Is it better to have one large life insurance policy or two smaller policies?
It depends on your financial goals. One larger policy may be simpler to manage, while multiple smaller policies can provide flexibility for different coverage periods and financial obligations. Compare total premiums and policy conditions.
What happens if I have two life insurance policies and die?
Your beneficiaries can generally submit separate claims and receive the approved death benefit from each active policy, subject to its contract terms.
Can I have life insurance through my employer and a private insurance company?
Yes. Employer-sponsored group life insurance can generally be combined with individual coverage. Check the workplace plan’s limits, portability, and conversion options.
Do beneficiaries pay taxes on two life insurance payouts?
Generally, death benefits are not taxable as income under federal tax rules, even when beneficiaries receive payments from multiple policies. Interest and certain special arrangements may have different tax treatment.
Can an insurance company reject my second life insurance application?
Yes. An insurer may decline or reduce requested coverage based on health, financial justification, underwriting standards, or other risk factors. Disclose existing coverage accurately.
Final Takeaway
Having more than one life insurance policy in the USA is generally permitted and can help families protect different financial responsibilities. Two policies can provide separate death benefits, provided both remain valid and the claims meet their contractual requirements.
Before buying additional coverage in 2026, compare term and whole life premiums, calculate your family’s actual financial needs, disclose existing policies, and review the insurer’s terms carefully. The goal is not to own the most policies; it is to secure enough affordable protection for the people who depend on you.
