
Subheadline: While SPX Technologies (NYSE: SPXC) posted robust double-digit sales growth and outperformed Q3 expectations, capacity-related costs and inflation in its HVAC segment prompted Truist Securities to cut its target, highlighting margin pressures going forward.
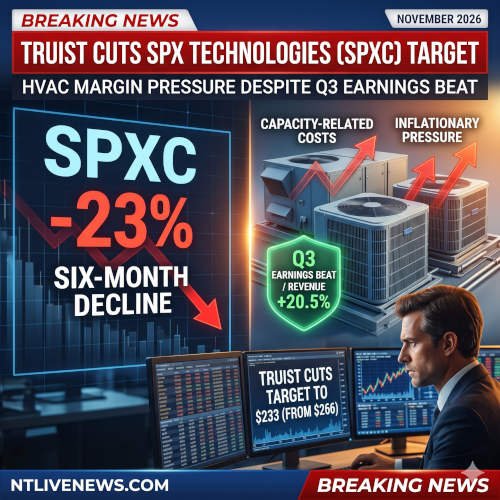
NEW YORK — SPX Technologies (NYSE: SPXC) recently reported strong third-quarter 2026 financial results that exceeded Wall Street estimates on both top and bottom lines, yet the stock remains under pressure. In response to recent guidance adjustments and margin headwinds within the company’s Heating, Ventilation, and Air Conditioning (HVAC) segment, Truist Securities has lowered its price target on SPX Technologies to $233 from $266, though it maintained a Buy rating on the stock.
The adjustment highlights the complex dynamics facing SPXC: while the company is seeing robust organic demand and expansion in data center-related revenue, capacity-related costs and inflationary pressures are squeezing margins in its largest business segment.
Here is a comprehensive look at SPX Technologies’ latest earnings, its adjusted outlook, and the market factors influencing Truist’s decision.
Strong Q3 Results Beat Wall Street Estimates
For the third quarter of 2026, SPX Technologies delivered an impressive performance, continuing its trend of more than 20% year-over-year earnings growth for the fifth consecutive quarter.
- Adjusted EPS: SPXC reported adjusted earnings per share of $2.21, surpassing the consensus Wall Street estimate of $2.13 and B. Riley’s projections.
- Total Revenue: Revenue reached $714.5 million, up 20.5% year-over-year, which beat the consensus forecast of $710.4 million. This was driven by a strong organic growth rate of 11.8%.
- Adjusted EBITDA: The company posted an adjusted EBITDA of $165.7 million (reported by Truist as $166 million), slightly ahead of the consensus of $164.4 million to $165 million.
Despite these strong headline figures, SPXC’s stock has faced significant downward pressure, declining 23% over the past six months. On the day of the updates, the stock was trading around $159.95, giving the company a market capitalization of approximately $8.01 billion.
HVAC Margin Pressures Drive Guidance Cut
The primary catalyst for Truist’s price target reduction is the margin pressure within SPX’s HVAC segment, which has been impacted by capacity-related costs and inflation.
While HVAC revenue grew a massive 35.5% year-over-year to $525 million (boosted by 22.3% organic growth and a 13.0% contribution from recent acquisitions), the segment’s operating margin fell by 140 basis points to 23.0%. Management acknowledged that these capacity constraints and inflationary pressures would continue to weigh on the segment’s performance through the fourth quarter.
As a result, SPX Technologies adjusted its full-year 2026 guidance:
- Revenue Guidance: Raised by $40 million at the midpoint to $2.775 billion, reflecting robust ongoing demand.
- Adjusted EPS Guidance: Trimmed by $0.05 at the midpoint to $8.35.
- Adjusted EBITDA Guidance: Lowered by $10 million at the midpoint to $635 million.
These revisions have prompted caution among some market observers. According to InvestingPro data, eight analysts have revised their earnings expectations downward for the upcoming period. However, SPXC maintains a “GOOD” financial health score of 2.68 on InvestingPro, suggesting the underlying business remains resilient despite short-term margin headwinds.
Strength in Detection & Measurement and Data Centers
While the HVAC segment is experiencing growing pains, other areas of SPX’s portfolio showed notable strength and margin expansion.
The Detection and Measurement segment saw its revenue decline 7.7% year-over-year to $189.5 million due to the timing of specific projects. However, the segment’s operating margin expanded significantly, rising 260 basis points to 27.8%, driven by favorable mix and operational efficiencies.
Furthermore, SPXC is successfully capturing the surging demand from the data center boom. The company increased its 2026 data center revenue forecast to a range of $450 million to $460 million, up from its previous estimate of approximately $430 million (excluding its Neptronic and FIS Water businesses).
Truist and B. Riley Maintain Bullish Stance
Despite lowering the price target to reflect the near-term margin squeeze, Truist Securities remains optimistic about SPX Technologies’ long-term trajectory. Truist updated its future adjusted EPS estimates, forecasting continued growth:
- Fiscal 2026 EPS Estimate: $8.40
- Fiscal 2027 EPS Estimate: $9.55
- Fiscal 2028 EPS Estimate: $11.00
At the new $233 target, Truist still sees substantial upside from SPXC’s current trading price of around $160.
Similarly, B. Riley reiterated its Buy rating on the stock with a $250 price target following the earnings release. The firm praised SPX’s ability to consistently beat revenue and earnings expectations, noting that overall demand remains upbeat despite the HVAC margin headwinds. B. Riley’s analysts highlighted that the positive demand environment, particularly in high-growth areas like data centers, bodes well for the company’s ability to navigate current inflationary and capacity challenges.
For investors, the recent 23% pullback may represent an intriguing entry point into a company with five consecutive quarters of 20%+ earnings growth, even as it works through temporary operational bottlenecks to meet robust market demand.
