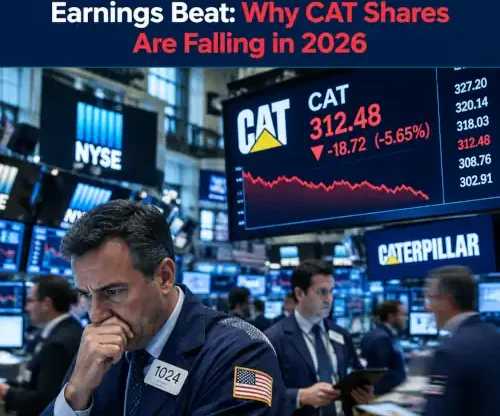

Caterpillar stock (NYSE: CAT) came under heavy selling pressure on October 29, 2026, despite reporting stronger-than-expected adjusted earnings and a record order backlog. The sell-off highlights growing investor concerns about the sustainability of the artificial intelligence infrastructure boom, tariff-related costs, and the outlook for future sales growth.
The heavy-equipment manufacturer reported third-quarter revenue of $20.7 billion, up 17% from the same period last year. Adjusted earnings reached $7.20 per share, beating analysts’ expectations. Its order backlog also climbed to a record $78.1 billion.
However, the earnings beat was not enough to satisfy investors. Revenue fell slightly short of analyst estimates, tariff recoveries contributed to operating profit, and management’s forecast for moderate fourth-quarter sales growth offered limited reassurance to a market accustomed to stronger results.
Caterpillar shares fell sharply during Thursday’s session, while the Dow Jones Industrial Average experienced a much smaller decline. The reaction demonstrates how expectations, rather than headline earnings alone, can drive stock market movements.
Caterpillar Stock Price Falls Despite Strong Third-Quarter Earnings
Caterpillar’s latest earnings report presented a business that was growing across its major operating segments. Yet investors focused on the gap between strong historical results and expectations for continued growth.
According to the company’s October 29 earnings release, third-quarter sales and revenues increased to $20.7 billion from $17.6 billion a year earlier. Adjusted profit per share rose to $7.20 from $4.95 in the third quarter of 2025.
The company also reported operating profit of approximately $4.21 billion, compared with $3.05 billion in the prior-year quarter. Its operating profit margin improved to 20.4% from 17.3%.
Nevertheless, revenue narrowly missed analysts’ consensus estimates. That shortfall was important because Caterpillar had benefited from strong demand for construction equipment, industrial power systems, and machinery used in data-center development.
The stock had also experienced a substantial rally earlier in 2026. According to Yahoo Finance’s October 29 report, Caterpillar gained approximately 86% through the first half of the year, making it the Dow’s strongest performer over that period.
When a stock has already climbed significantly, investors may expect results that exceed forecasts by a wide margin. Even a profitable quarter can trigger selling if the outlook suggests that future growth may be less impressive.
The immediate decline therefore reflects concerns about expectations and valuation, rather than evidence that Caterpillar’s entire business has suddenly deteriorated.
Why CAT Stock Is Falling
Three factors help explain why Caterpillar shares declined despite the earnings beat.
First, revenue growth did not fully meet expectations. Caterpillar’s $20.7 billion in quarterly revenue represented a strong year-over-year increase, but the figure was slightly below analysts’ estimates. Investors were looking for evidence that the company’s growth momentum could continue at a similarly strong pace.
Second, tariff recoveries supported reported profit. Caterpillar’s third-quarter operating profit included $128 million in recoveries related to tariffs imposed under the International Emergency Economic Powers Act. The benefit contributed to the reported results, prompting investors to examine how much of the earnings strength came from underlying operations.
The company has also estimated approximately $2.2 billion in tariff costs for 2026 before applicable recoveries. Tariffs can affect manufacturing expenses, supply chains, equipment pricing, and profit margins.
Third, management’s sales outlook disappointed some investors. Caterpillar maintained its full-year expectation for sales growth in the mid-to-high teens but indicated that fourth-quarter sales growth would be moderate.
That outlook appeared less optimistic than some market participants had anticipated. Investors were particularly attentive to whether strong demand from data centers and other infrastructure projects could continue supporting the company’s growth.
These factors combined to create a difficult reaction: earnings were higher, but the results did not eliminate concerns about future profitability, costs, and demand.
Why Caterpillar Stock Became a Market Favorite
Artificial intelligence infrastructure has become an important theme for investors evaluating industrial companies.
AI systems require substantial computing capacity, which depends on data centers, electrical infrastructure, cooling equipment, and reliable power supplies. Building these facilities creates demand for equipment and services across several industries.
Caterpillar benefits from this trend through its Power & Energy business, which supplies power-generation equipment and related products used in applications that include data centers.
In the third quarter of 2026, the Power & Energy segment generated approximately $8.78 billion in sales, an increase of 18% from the previous year. Segment profit increased to approximately $2.14 billion.
The results demonstrate that power-related demand remains an important source of growth for the company.
Caterpillar also reported strong sales in its other major segments. Construction Industries generated approximately $7.98 billion in revenue, while Resource Industries recorded about $4.62 billion.
These businesses serve construction, mining, infrastructure, and other industrial markets, giving Caterpillar exposure beyond the AI sector.
However, investors are increasingly asking whether spending on AI infrastructure can maintain its current pace. Large technology companies are investing heavily in data centers, but questions remain about project timelines, electricity availability, financing, and the eventual returns on AI investment.
If data-center construction continues expanding, Caterpillar could benefit from demand for power equipment and associated infrastructure. If spending slows or projects are delayed, some of the growth expectations supporting its valuation could weaken.
The company’s recent share-price decline illustrates how quickly sentiment can change when investors begin questioning the durability of a popular investment theme.
What Investors Should Watch Next
Caterpillar’s record order backlog provides an important indicator of future business activity. At approximately $78.1 billion, the backlog shows that the company has substantial orders awaiting fulfillment.
However, a backlog is not the same as guaranteed future revenue or profit. Orders may be delivered over different periods, and the financial contribution of each order depends on pricing, costs, production schedules, and customer requirements.
Investors following the Caterpillar stock forecast should monitor several developments.
Revenue growth: Future quarterly results will help determine whether demand across construction, mining, and power generation remains strong.
Operating margins: Investors will want to understand whether Caterpillar can maintain profitability while managing manufacturing expenses, freight costs, and tariffs.