
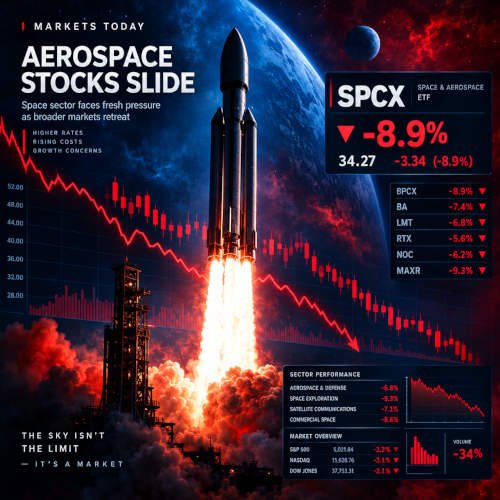
Stock Market Updates: SpaceX stock has entered November 2026 under pressure after losing nearly 9% of its market value during October. The decline has raised questions about whether investors should buy the aerospace and artificial intelligence company’s shares following its latest earnings announcement.
SpaceX has become one of the most closely watched technology stocks since its historic initial public offering on June 12, 2026. Trading under the ticker SPCX on Nasdaq, the company offers investors exposure to commercial space launches, satellite broadband, artificial intelligence and computing infrastructure.
Despite its impressive business growth, the latest share-price weakness highlights an important investment question: Is SpaceX stock worth buying simply because its business is expanding rapidly?
The company’s third-quarter financial results were impressive. Revenue increased 161% year over year to approximately $14.6 billion, while net income reached $4.4 billion. Nevertheless, growing infrastructure costs, ambitious expansion plans and valuation concerns could create challenges for shareholders.
Why SpaceX Stock Fell in October 2026
SpaceX shares experienced significant volatility during October as investors reconsidered the valuations of companies with substantial artificial intelligence exposure.
The company is no longer viewed exclusively as a rocket manufacturer. Its expanding AI infrastructure business has become an important part of its growth strategy, increasing its exposure to the technology sector.
Investors are also examining how much capital SpaceX needs to maintain its competitive position across several industries.
The October decline does not necessarily indicate deteriorating business performance. Instead, it demonstrates how quickly market sentiment can change when investors become concerned about expensive growth stocks.
According to historical market data, SPCX lost approximately 8.7% over the month through October 30.
Strong Earnings Have Not Eliminated Investment Concerns
SpaceX’s latest quarterly earnings report showed substantial improvements across its businesses.
However, investors should distinguish between revenue growth, operating profitability and the amount of money a company must spend to achieve future expansion.
SpaceX operates in industries where maintaining a technological advantage requires substantial investment. Rocket development, satellite manufacturing, data centres and AI computing infrastructure all involve significant financial commitments.
A company can report impressive quarterly revenue while still facing questions about the sustainability of its spending and future returns.
SpaceX Q3 2026 Earnings: Revenue Climbs 161%
SpaceX reported third-quarter 2026 revenue of approximately $14.6 billion, representing 161% growth compared with the same period last year.
The company also reported $4.4 billion in net income and $8.8 billion in adjusted EBITDA.
These figures demonstrate the scale of its expanding operations.
Its business is organised into three major segments:
- Space: Rocket development, manufacturing and commercial launch services.
- Connectivity: Starlink satellite internet and related communication services.
- Super Intelligence: Artificial intelligence infrastructure, Grok, Cursor and related technology products.
The results show that SpaceX is building a diversified technology business rather than depending exclusively on rocket launches.
Starlink Continues to Strengthen SpaceX’s Revenue Base
Starlink remains one of SpaceX’s most important commercial opportunities.
Its satellite broadband network serves consumers, businesses and government customers across international markets.
The company’s third-quarter filing reported connectivity revenue of approximately $5.25 billion, up 69.5% year over year.
Consumer subscriber growth, enterprise agreements and government demand contributed to the expansion.
However, investors should also consider the costs of launching additional satellites, maintaining network infrastructure and expanding service coverage.
Growth in subscriptions is valuable, but shareholders ultimately need evidence that the business can convert that growth into sustainable profits and cash flow.
Artificial Intelligence Expansion Adds Another Growth Opportunity
Artificial intelligence has become a major part of SpaceX’s long-term strategy.
Its Super Intelligence segment generated approximately $7.56 billion in third-quarter revenue, making it the company’s largest revenue segment during the period.
The segment includes AI infrastructure, Grok and Cursor-related operations.
This expansion gives SpaceX access to a rapidly growing market, but it also introduces additional competitive and financial risks.
Companies developing advanced AI systems must invest continuously in computing capacity, specialised hardware, data centres and research.
Competition from established technology companies could also put pressure on pricing and future profitability.
- The Biggest Concern: SpaceX’s Spending and Valuation
Strong quarterly earnings are attractive, but they do not automatically make SPCX stock inexpensive.
Investors must examine how much they are paying for future growth.
SpaceX’s valuation reflects expectations that its businesses will continue expanding rapidly. If growth slows or anticipated projects take longer than expected, the stock could face further pressure.
The company’s September 2026 quarterly filing also highlighted substantial capital requirements.
Capital expenditure across its three business segments reached approximately $19.6 billion during the third quarter alone, while spending for the first nine months of 2026 totalled approximately $48.1 billion.
These investments support the company’s ambitious expansion plans, but they also demonstrate the financial scale required to maintain its growth strategy.
Why High Valuations Can Become a Problem
Investors buying expensive growth stocks often depend on future earnings to justify today’s share prices.
If those earnings arrive later than expected, market sentiment can change quickly.
SpaceX faces several important challenges:
- Maintaining strong Starlink subscriber growth.
- Generating attractive returns from AI infrastructure.
- Managing Starship development costs.
- Competing with established AI technology companies.
- Controlling capital expenditure as operations expand.
These factors do not mean SpaceX will fail. They simply demonstrate why investors should examine the company’s financial position rather than focusing entirely on its ambitious future plans.
SpaceX Stock Outlook for November 2026
The November outlook for SpaceX shares depends on several factors, including technology-sector sentiment, AI investment trends and the company’s ability to demonstrate sustainable financial performance.
A further decline could attract investors who believe the company’s long-term prospects remain strong.
However, buying after a stock falls is not automatically a profitable strategy.
Investors should consider whether the current valuation already reflects the company’s expected growth.
The company’s next financial updates will be important for understanding whether Starlink, AI infrastructure and commercial launch services can continue supporting its expansion.
Should Investors Buy SpaceX Stock in November?
SpaceX offers exposure to several potentially transformative industries. Its reusable rocket technology, Starlink network and AI infrastructure create significant long-term opportunities.
Nevertheless, investors should not overlook the risks associated with its valuation and capital-intensive expansion.
A cautious approach may make sense for investors who believe the stock price has moved ahead of the company’s sustainable earnings potential.
Before purchasing SPCX shares, investors should examine quarterly financial statements, operating cash flow, capital expenditure, competitive pressures and valuation metrics.
Those who already own the stock may also want to review their portfolio exposure and risk tolerance.
Final Takeaway: SpaceX Has Growth Potential, but the Price Matters
SpaceX’s October share-price decline presents an interesting situation for investors entering November 2026.
The company delivered impressive third-quarter results, with revenue reaching approximately $14.6 billion and net income totalling $4.4 billion.
Starlink continues to expand, while artificial intelligence infrastructure creates another major growth opportunity.
However, ambitious expansion plans require substantial capital, and the stock’s valuation leaves investors with important questions about future returns.
The key lesson is simple: A successful company is not necessarily a good investment at every price.
Investors considering SpaceX stock should balance its extraordinary technological opportunities against its spending requirements, competitive risks and market valuation. Waiting for greater clarity about sustainable profitability may be more appropriate than buying simply because shares have fallen.
