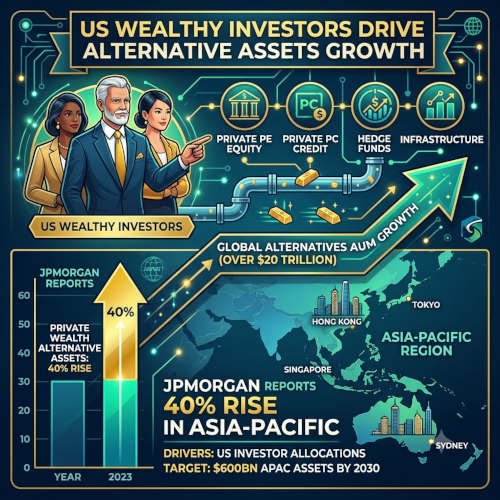
Wealthy investors are increasing their exposure to alternative investments across Asia-Pacific, creating a major growth opportunity for global asset managers. JPMorgan Asset Management has reported a 40% year-over-year increase in private wealth alternative assets in the region, highlighting stronger demand for investment strategies beyond traditional stocks and bonds.
The growth reflects rising interest among high-net-worth and ultra-high-net-worth investors in hedge funds, private equity, infrastructure and other alternative asset classes. These investments can offer different sources of returns and portfolio diversification, although they also carry risks such as limited liquidity, higher fees and complex valuations.
The latest figures were highlighted by Dan Watkins, Asia-Pacific chief executive of JPMorgan Asset Management, during a media briefing in Singapore. The development also supports the company’s broader ambition to expand its regional asset base and strengthen its private wealth business.
For investors following JPMorgan Chase (NYSE: JPM), the trend is important because asset and wealth management can generate recurring fee income. It also shows how financial institutions are competing for a larger share of the growing private investment market.
JPMorgan Alternative Assets Growth Reaches 40% in Asia-Pacific
JPMorgan Asset Management reported that its private wealth alternative investments in Asia-Pacific increased 40% over the 12 months leading up to the November 2026 report.
The expansion came alongside a 50% increase in the company’s regional private-bank assets over the same period. These figures suggest that wealthy clients are becoming an increasingly important source of growth for the asset-management business.
According to Watkins, demand for alternative investment exposure has been particularly strong among ultra-high-net-worth and high-net-worth investors.
The figures point to a broader change in how affluent investors approach portfolio construction. Instead of relying entirely on listed equities, government bonds and traditional investment funds, some wealthy clients are allocating more capital to private markets and specialist investment strategies.
However, the 40% increase refers specifically to private wealth alternative investments in Asia-Pacific. It should not be interpreted as a 40% increase in all JPMorgan assets under management or the entire global alternatives business.
Why Wealthy Investors Are Choosing Alternative Assets
Alternative investments include financial assets and strategies outside conventional publicly traded stocks and bonds. They can include private equity, hedge funds, private credit, infrastructure, real estate and natural resources.
These investments appeal to some wealthy investors because they offer access to different markets, businesses and sources of potential returns.
Private equity, for example, allows investors to gain exposure to privately owned companies. Infrastructure investments can provide exposure to long-term projects involving transportation, energy, utilities and digital infrastructure.
Hedge funds use different investment strategies, including long-short equity, macroeconomic trading and event-driven approaches. Private credit funds provide loans to businesses outside traditional public bond markets.
The growing demand for these products reflects investors’ interest in diversifying their portfolios and accessing opportunities that may not be available through conventional investment funds.
Nevertheless, alternative assets are not automatically safer or more profitable than traditional investments. Their performance depends on investment selection, market conditions, fees, financing arrangements and the ability to exit investments.
JPMorgan Targets $600 Billion in Asia-Pacific Assets by 2030
JPMorgan Asset Management has set an ambitious regional growth target. The company is aiming to increase its Asia-Pacific assets to $600 billion by 2030.
According to a report published by Dow Jones on October 27, 2026, Watkins said the business was making progress toward this target and was nearly one-third of the way there after approximately one year.
The expansion is being supported by several regional markets, including China, Australia and Japan.
These economies offer different opportunities for asset managers. China remains an important market because of its large investor base and developing investment industry. Australia has an established retirement and wealth-management sector, while Japan has attracted renewed interest following economic and financial-market changes.
The private wealth business is becoming an important growth driver alongside institutional clients.
Institutional investors remain a major part of the regional asset-management industry. However, increasing demand from wealthy individuals and family offices gives JPMorgan another opportunity to expand its business.
Exchange-Traded Funds Add Another Growth Opportunity
JPMorgan Asset Management is also expanding its regional exchange-traded fund business.
Watkins said the company’s Asia-Pacific ETF business had grown fivefold since 2022. This expansion provides another example of the firm’s efforts to attract investors through different investment products.
ETFs are investment funds traded on stock exchanges. They can provide exposure to individual markets, sectors, bonds and investment strategies.
Unlike many private-market funds, publicly traded ETFs generally offer investors greater trading flexibility. Their growth therefore represents a different opportunity from the expansion of private wealth alternative investments.
Together, these developments show how JPMorgan is pursuing growth across both traditional investment products and private-market strategies.
What Is Driving Alternative Assets Growth Among High-Net-Worth Investors?
Several factors are contributing to the increasing interest in alternative assets across Asia-Pacific.
One important factor is the growing wealth of affluent households and family offices. As investors accumulate more financial resources, they may seek access to investment opportunities beyond conventional public markets.
Another factor is the changing investment environment. Inflation uncertainty, interest-rate movements, geopolitical developments and market volatility have encouraged investors to reconsider how they diversify their portfolios.
Private markets can provide exposure to businesses and assets that do not trade daily on public exchanges. Some investors believe these investments can complement traditional stock and bond holdings over longer periods.
Infrastructure is another important area of interest. The expansion of artificial intelligence, cloud computing and digital services has increased demand for data centers, electricity networks and supporting infrastructure.
These developments could create opportunities for infrastructure funds and other private investment strategies. However, investment outcomes depend on project costs, financing conditions, regulation and long-term demand.
Private Equity, Hedge Funds and Infrastructure Attract Attention
Private equity is one of the most established alternative investment categories. It involves investing in privately held companies, often with the objective of improving business performance and increasing their value over several years.
Hedge funds use a wider range of strategies and can invest across different asset classes. Some aim to generate returns through market movements, company-specific opportunities or differences in asset valuations.
Infrastructure investments focus on essential physical and digital assets. These can include roads, airports, power networks, renewable energy projects, transportation systems and data centers.
Private credit is another growing alternative investment category. It involves lending directly to companies or providing financing through private funds rather than relying exclusively on traditional banks or public bond markets.
Each category has different investment characteristics. Investors must consider the potential return, fees, borrowing exposure, valuation methods and liquidity restrictions before committing capital.
JPMorgan’s Wealth Management Business Shows Strong Financial Scale
The growth in private wealth alternatives comes as JPMorgan Chase continues to report substantial activity across its global asset and wealth management operations.
In its third-quarter 2026 results, JPMorgan reported approximately $5.2 trillion in assets under management, representing a 13% increase from the same period in 2025.
The bank also reported $7.9 trillion in client assets, up 15% year over year.
Asset and Wealth Management generated approximately $6.9 billion in third-quarter revenue, an increase of 14% compared with the previous year. Net income reached approximately $1.8 billion, up 11%.
The results reflect the scale of JPMorgan’s investment-management operations and the importance of market performance, client activity and new money flows.
The company reported $51 billion in long-term net inflows during the quarter, alongside $42 billion in liquidity net inflows.
These figures are relevant because asset managers typically earn fees based on the assets they manage. When client assets increase through new investments or market appreciation, management-fee revenue can also benefit.
However, the relationship is not automatic. Fee rates vary by product, and some alternative investments have different fee structures from traditional funds.
Why Alternative Assets Growth Matters for JPM Stock Investors
JPMorgan Chase investors may view the expansion of private wealth alternatives as a positive development for the company’s long-term asset-management strategy.
Wealth management can provide recurring revenue through investment-management and advisory fees. These revenue streams can complement the bank’s other businesses, including consumer banking, commercial banking, investment banking and trading.
Alternative investments may also offer opportunities to build deeper relationships with wealthy clients. Investors who use several products and services may maintain broader relationships with the financial institution.
For JPM shareholders, the key issue is whether the growth in alternative assets can translate into sustainable revenue and profitability.
However, investors should not assume that a 40% increase in one regional business automatically produces a similar increase in JPMorgan’s overall earnings.
The bank’s performance depends on many factors, including interest rates, loan demand, credit losses, trading activity, investment banking fees, operating expenses and financial-market conditions.
JPMorgan’s third-quarter results showed that its overall business remained large and profitable, but the private wealth alternatives figure represents only one part of the company’s operations.
Risks Wealthy Investors Should Understand Before Buying Alternative Assets
Despite growing interest, alternative investments carry important risks.
Liquidity is one of the biggest considerations. Private equity, private credit and infrastructure funds may require investors to keep their money invested for several years. Selling an investment quickly may be difficult or impossible under certain fund structures.
Valuation is another challenge. Publicly traded stocks receive frequent market prices, while private assets may be valued periodically using estimates and financial models.
Fees can also be higher. Some alternative funds charge management fees and performance-based fees, which can reduce the investor’s final returns.
Leverage creates additional risk. Certain funds borrow money to increase their investment exposure. Although leverage can amplify gains, it can also magnify losses.
Investors should review the fund’s structure, redemption conditions, investment strategy, expenses and regulatory disclosures before making a decision. Alternative investments are not suitable for every investor and do not guarantee diversification or positive returns.
What Comes Next for JPMorgan’s Asia-Pacific Wealth Business?
JPMorgan’s reported 40% growth in private wealth alternative investments highlights the increasing importance of wealthy clients in the Asia-Pacific investment market.
The company’s $600 billion regional asset target provides a clear indication of its long-term ambitions. Growth in private banking, ETFs and alternative investment products could help it expand its presence across major Asian financial markets.
The next stage will depend on whether client demand remains strong and whether the company can convert that interest into sustainable assets under management and fee revenue.
Investors will also monitor competition, market valuations, regulation and the performance of private-market strategies.
For JPMorgan Chase, the expansion of alternative assets represents a significant business opportunity. For wealthy investors, it reflects a changing investment landscape in which private markets are becoming a more prominent part of portfolio discussions.
However, strong growth in demand does not remove the risks. The quality