The Internal Revenue Service (IRS) has announced new federal income tax adjustments for the 2027 tax year, giving millions of American taxpayers updated deduction limits, income tax brackets and tax credit amounts.
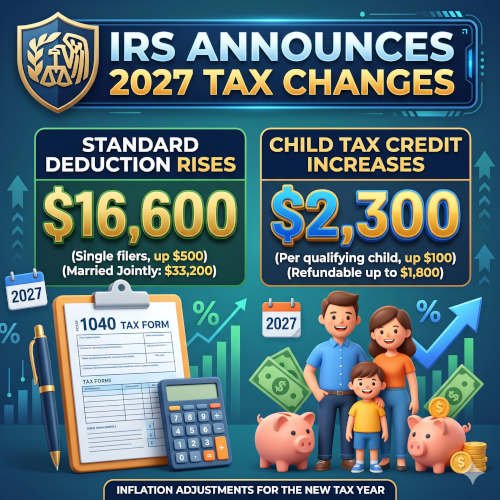
Under the latest announcement, the standard deduction for single taxpayers will increase to $16,600, while married couples filing jointly will receive a deduction of $33,200. The maximum Child Tax Credit will also rise to $2,300, providing an additional tax benefit for eligible families.
The changes are part of the IRS’s annual inflation adjustments, which affect nearly 70 tax provisions. They are designed to account for changes in prices and prevent inflation from pushing taxpayers into higher tax brackets without a corresponding increase in their purchasing power.
The new amounts apply to income earned during the 2027 calendar year. Americans will generally claim these deductions and credits when they file their 2027 federal income tax returns in 2028.
What Are the Biggest IRS Tax Changes for 2027?
The 2027 IRS tax changes include higher standard deductions, updated federal income tax brackets, an increased Child Tax Credit and adjustments to several other tax benefits.
The most important changes for individual taxpayers include:
- Single filers: Standard deduction increases to $16,600.
- Married couples filing jointly: Standard deduction rises to $33,200.
- Heads of household: Standard deduction increases to $24,925.
- Child Tax Credit: Maximum credit increases to $2,300 per qualifying child.
- Refundable Child Tax Credit: The maximum refundable amount rises to $1,800.
- Earned Income Tax Credit: The maximum credit for qualifying taxpayers with at least three children increases to $8,496.
These adjustments may affect how much taxable income Americans report and the credits they can claim. However, the actual tax savings will depend on income, filing status, household circumstances and eligibility requirements.
2027 Standard Deduction: How Much Can Taxpayers Claim?
The standard deduction is one of the most important parts of the federal income tax system. It reduces the amount of income subject to federal income tax before the IRS calculates a taxpayer’s final liability.
Most Americans claim the standard deduction instead of itemizing individual expenses. The increase for 2027 means eligible taxpayers can subtract a larger amount from their income before calculating their federal income tax.
The IRS announced the following standard deduction amounts:
| Filing Status | 2026 Standard Deduction | 2027 Standard Deduction |
|---|---|---|
| Single | $16,100 | $16,600 |
| Married filing jointly | $32,200 | $33,200 |
| Married filing separately | $16,100 | $16,600 |
| Head of household | $24,150 | $24,925 |
For single taxpayers, the deduction increases by $500 compared with 2026. Married couples filing jointly receive a $1,000 increase, while heads of households receive an additional $775.
For example, a single taxpayer earning $60,000 in 2027 who qualifies for the full $16,600 standard deduction would generally have $43,400 remaining before other applicable deductions and adjustments are considered.
This does not mean the taxpayer will automatically owe tax on exactly $43,400. Other deductions, credits, income adjustments and tax rules may affect the final calculation.
Standard Deduction vs. Itemized Deductions
Taxpayers generally choose between claiming the standard deduction and itemizing eligible expenses.
The standard deduction offers a fixed amount based on filing status. Itemized deductions allow eligible taxpayers to report specific expenses, which may include qualifying mortgage interest, charitable contributions and certain state and local taxes.
The better option depends on an individual’s financial situation. Taxpayers with substantial eligible deductible expenses may benefit from itemizing, while others may find the standard deduction more valuable.
Comparing both options before filing can help taxpayers make better tax planning decisions.
IRS Announces New Federal Income Tax Brackets for 2027
The IRS has also adjusted federal income tax brackets for 2027. These thresholds determine which marginal tax rates apply to different portions of a taxpayer’s taxable income.
The United States uses a progressive income tax system. This means taxpayers do not pay one tax rate on their entire income. Instead, different portions of taxable income are taxed at different rates.
The seven federal income tax rates remain unchanged at 10%, 12%, 22%, 24%, 32%, 35% and 37%. However, the income thresholds for these rates have increased.
The following table shows the 2027 federal income tax brackets for single filers and married couples filing jointly.
| Federal Tax Rate | Single Filers | Married Filing Jointly |
|---|---|---|
| 10% | $12,800 or less | $25,600 or less |
| 12% | Over $12,800 | Over $25,600 |
| 22% | Over $52,025 | Over $104,050 |
| 24% | Over $109,125 | Over $218,250 |
| 32% | Over $208,325 | Over $416,650 |
| 35% | Over $264,550 | Over $529,100 |
| 37% | Over $661,375 | Over $793,650 |
These are the income thresholds at which the corresponding marginal tax rates begin. Each rate applies only to the portion of taxable income within that bracket.
For example, a single taxpayer with taxable income above $52,025 does not pay 22% on every dollar earned. The lower portions of taxable income remain subject to the lower applicable rates.
Understanding marginal tax rates is important for financial planning, estimating federal income tax liability and evaluating the effect of additional income.
Child Tax Credit Increases to $2,300 in 2027
Families with qualifying children will also see an increase in the Child Tax Credit.
The IRS confirmed that the maximum Child Tax Credit will rise to $2,300 for the 2027 tax year, compared with $2,200 in 2026. The maximum refundable portion will increase from $1,700 to $1,800.
This adjustment could provide additional financial support to eligible households dealing with childcare expenses, housing costs, groceries and